For business owners across British Columbia, Alberta, and Saskatchewan, receiving the annual group benefits renewal package often feels like receiving a mystery bill. You open the envelope (or PDF), skip past the colorful charts, and scan straight to the bottom line—only to discover your monthly premiums are jumping by 15%, 20%, or more.
The immediate reaction is almost always frustration. You look back at the past year and think: “Nobody had a major surgery, we didn’t hire twenty new people, and we barely changed our coverage. How can our rates possibly jump this much?”
When you call your traditional insurance broker or carrier for an explanation, you are usually met with vague industry jargon about “market inflation,” “drug cost trends,” or “claims pooling.”
To take control of your employee benefits budget, you need to lift the curtain on how insurance carriers actually calculate your rates. Specifically, you need to understand the fundamental mechanics separating Pooled Claims from Experience-Rated Claims—and why traditional pooling models often force small and mid-sized Western Canadian businesses to pay for other companies’ bad luck.
1. The Financial Engine: How Carriers Split Your Plan
When an insurance company sets your annual renewal rates, they do not treat your entire benefits package as a single bucket of money. Instead, they divide your coverage into two distinct financial categories: Pooled Risk and Experience-Rated Risk.
Pooled Claims (Catastrophic Protection)
Pooled coverage protects against unpredictable, high-cost, or catastrophic events. This category includes Life Insurance, Accidental Death & Dismemberment (AD&D), Long-Term Disability (LTD), Critical Illness, and Stop-Loss protection (which caps high-cost specialty drug claims).
Because a single Long-Term Disability claim or catastrophic drug diagnosis could instantly bankrupt a small business’s benefit fund, the carrier spreads this risk across a massive “pool” of thousands of participating businesses across Western Canada.
Experience-Rated Claims (Everyday Usage)
Experience-rated coverage handles predictable, high-frequency, lower-cost healthcare needs. This category includes routine Health, Dental, Vision, and Paramedical services (like massage, chiropractic care, and physiotherapy), as well as standard prescription drugs.
For these lines of coverage, the carrier looks directly at your specific company’s claims history over the past 12 to 24 months. If your team submitted $20,000 in dental and health claims, the carrier calculates how much premium they need to collect next year to cover that $20,000, plus their administrative overhead, inflation adjustments, and profit margin.
2. The Small Business Trap: Fully Pooled Small Group Plans
If your company has fewer than 20 or 25 employees, traditional insurance carriers treat you differently. Because a small workforce does not generate enough statistical volume for pure experience rating, many insurers place small employers into Fully Pooled Small Business Plans.
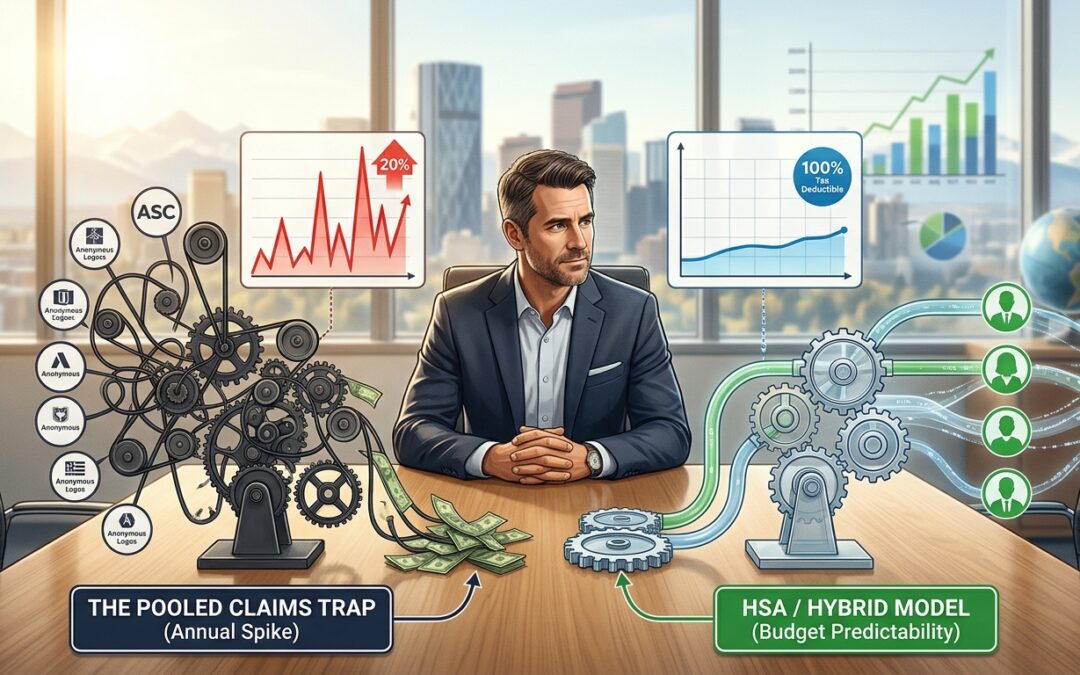
Under a fully pooled plan, your health and dental rates are not calculated solely on what your employees actually spent. Instead, your claims are blended with hundreds of other small businesses in your region.
This creates two distinct financial traps for Western Canadian employers:
- Paying for Other Companies’ Inflation: If your ten employees were extremely healthy and only claimed 40% of the premiums you paid into health and dental, but the broader small-business pool experienced heavy utilization, your rates still go up. You are effectively subsidizing the claims of competing businesses down the street.
- The “Trend Factor” Markup: Insurers apply an arbitrary “inflation and utilization trend factor” (often 8% to 14% annually) across health and dental lines. Even if your utilization remains completely flat, the baseline cost of the pool rises automatically every single year.
3. Decoding the Renewal Math: Why a 20% Jump Happens
When your renewal letter arrives with a 20% rate increase, it is rarely the result of a single factor. It is the cumulative effect of three compounding calculations applied by the carrier:
- Target Loss Ratio (TLR) Adjustments: Carriers design plans assuming that 70% to 75% of your premium goes toward paying claims, while 25% to 30% covers broker commissions, administration, and carrier profit. If your actual claims exceed that target threshold—even by a small margin—the carrier automatically hikes rates to re-establish their profit margin.
- Inflation and Cost Weighting: As provincial health authorities shift costs onto private plans and drug manufacturers launch high-cost biologics, carriers bake high trend projections into their forward-looking calculations.
- Inertia Pricing: Traditional insurance models rely heavily on client passivity. Insurers know that switching group carriers requires administrative effort for an employer. As a result, renewal pricing often carries an implicit “inertia markup”—testing whether the business owner will simply sign the increase to avoid administrative hassle.
4. Escaping the Rate-Hike Machine: The Hybrid HSA Solution
Business owners are not powerless against annual renewal spikes. You do not have to choose between absorbing unsustainable price hikes or stripping away valuable health coverage from your team.
The solution lies in decoupling your health coverage: insure the catastrophic risks, and fund the predictable routine care directly.
By transitioning from a rigid, fully pooled traditional policy to a Hybrid Benefits Architecture, you restructure how your corporate dollars are spent:
Keep Insurance for True Risk: Retain traditional pooled insurance for high-stakes, catastrophic protections that no small business should self-fund—such as Life, LTD, Travel, and Stop-Loss coverage.
Shift Health & Dental to an HSA: Replace the experience-rated/pooled health and dental portion with a Health Spending Account (HSA). You set a fixed annual dollar allocation per employee (e.g., $1,500/year).
Why the Hybrid Model Protects Your Bottom Line
When you route routine health and dental through an HSA, every dollar spent is 100% tax-deductible for your business and 100% tax-free for your employee. More importantly, you eliminate the carrier’s claims markup, target loss ratios, and pooled inflation surcharges. If an employee doesn’t use their full allocation, those dollars remain in your business account rather than padding an insurance carrier’s profit margin.
Take Control of Your Next Renewal
Your employee benefits program should be a predictable investment in workforce productivity, not a volatile financial liability.
Understanding the difference between pooled risks and experience-rated claims gives you the leverage needed to challenge arbitrary renewal hikes. By auditing your utilization data and embracing modern, hybrid spending models, you can protect your company’s cash flow, deliver exceptional care to your team, and exit the traditional rate-hike machine for good.