If you are a business owner or a highly compensated executive in British Columbia, Alberta, or Saskatchewan, your most valuable asset is not your real estate portfolio, your stock holdings, or your equipment. It is your ability to generate an income.
Yet, for many top-earners across Western Canada, this massive asset is dangerously under-insured, often without them knowing.
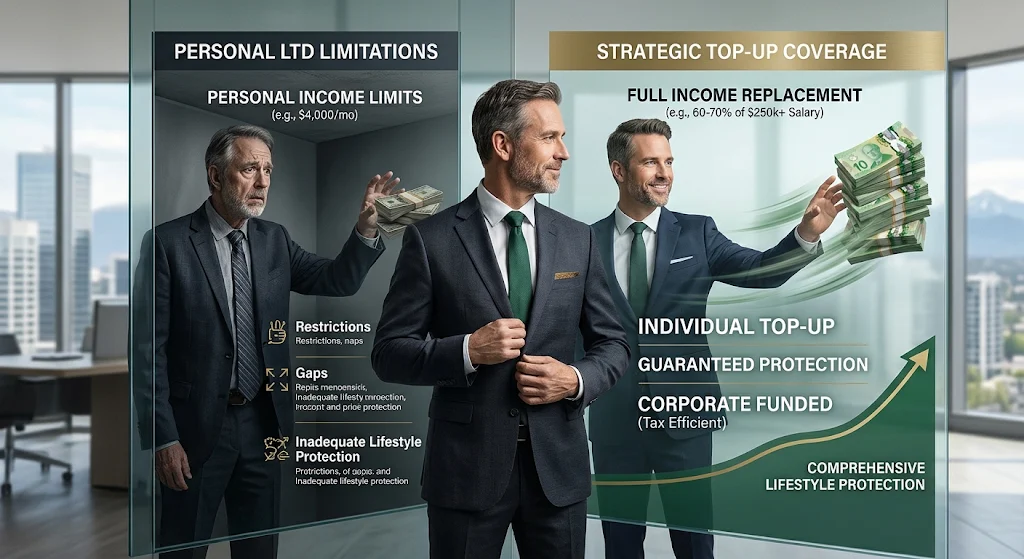
The culprit is the Disability Coverage Gap. While your company likely offers a standard group Long-Term Disability (LTD) plan that provides a sense of security, these programs are designed for the “average” employee. For anyone earning a high salary or accessing dividends, standard group LTD leaves a gaping, unmanaged financial risk.
If a sudden illness or accident prevents you from working, relying solely on your corporate plan could force you to face a sudden 50% or 60% drop in your monthly income. Closing that gap requires moving beyond generic, one-size-fits-all coverage and embracing strategic, individual “Top-Up” policies.
1. The Myth of the “Standard” 66.7% Protection
Most group insurance booklets contain reassuring language, promising employees that if they become totally disabled, they will receive 66.7% (two-thirds) of their pre-tax salary.
This sounds reasonable—enough to cover essential bills and maintain a basic lifestyle while focusing on recovery.
However, the fine print contains a devastating financial mechanism designed to limit the insurance carrier’s liability: the Monthly Maximum Cap. Standard group plans across Western Canada commonly cap monthly disability benefits at relatively low levels, often between $3,000 and $5,000 per month.
Consider the impact of this cap on a business owner or key executive:
Scenario A: The Average Employee (Covered)
- Annual Salary: $60,000 ($5,000/mo)
- Target Disability: 66.7% = $3,335/mo
- Plan Maximum: $5,000/mo
- Result: The employee receives the full $3,335 (all of their target protection). The standard plan works as intended.
Scenario B: The Business Owner or Top Executive (The Gap)
- Annual Earnings: $180,000 ($15,000/mo)
- Target Disability: 66.7% = $10,000/mo
- Plan Maximum: $5,000/mo
- Result: The owner receives only $5,000/mo. Their actual protection is only 33% of their pre-tax income—leaving a $5,000 monthly shortfall.
2. The Dividend Dilemma: The Risk of Self-Employment
This disability gap grows even wider for business owners who, like many entrepreneurs in Calgary, Vancouver, or Saskatoon, pay themselves primarily through dividends rather than salary for tax efficiency.
Standard group LTD carriers typically only insure “regular earned income”—meaning T4 salary. Because dividends are a distribution of corporate profit and not a contractually guaranteed paycheck, traditional disability plans ignore them entirely.
If your standard LTD plan provides 66.7% of $100,000 in T4 income, but you draw an additional $150,000 in dividends annually, your real total compensation of $250,000 is drastically under-insured. If you become disabled, your standard LTD payout will only replace a tiny fraction of the total income your family relies on to maintain your lifestyle.
3. The Consequences of Unmanaged Gap Risk
When high-income earners ignore this coverage gap, the consequences of a disability event can be emotionally and financially catastrophic.
Relying on generic group LTD forces you to face difficult choices during a recovery:
- Forced Lifestyle Degradation: Your $5,000 standard LTD payout cannot cover a $15,000 monthly burn rate. High-earners are forced to slash spending, sell properties, drain retirement savings, or disrupt children’s education plans.
- Depleting Corporate Assets: Healthy business owners are often forced to draw unmanageable amounts of capital from their operating corporations to maintain their families, straining the cash flow of the very business they cannot work in.
- Operational Control Risks: If a majority shareholder-owner cannot work but must still draw a high income to survive, it creates immense tension with healthy partners, often precipitating forced buyout negotiations or operational paralysis.
4. Closing the Gap: Strategic Individual Top-Up Policies
You are not locked into this exposure. As an independent benefits firm operating in BC, AB, and SK, ADI Benefits specializes in identifying and closing the high-earner gap through customized, Individual Disability “Top-Up” policies.
Unlike generic group plans, these policies are designed to layer directly over your existing corporate LTD coverage, bringing your total protection level up to 60% or 70% of your actual total compensation, including your dividends and salary bonuses.
The Benefits of Strategic individual Top-Ups:
- Guaranteed Income Replacement: You lock in full protection based on your true earnings profile, ensuring your lifestyle is not compromised.
- Corporate Ownership Option: Your company can own and pay for the individual Top-Up policy, creating a tax-efficient corporate expense while providing a critical executive-only perk.
- Enhanced Definitions of Disability: While group plans often switch to an “any occupation” definition (forcing you to work any job, like a Walmart greeter, if you are able) after 24 months, individual Top-Ups maintain an “Own Occupation” definition. If your disability prevents you from performing the material duties of your specific job as an executive/owner, you collect benefits, even if you are capable of other work.
- Permanent, Non-Cancelable Contracts: Your group plan can change carriers or categories at any time. A personalized individual policy is a guaranteed contract that stays in force, regardless of changes to your company’s structure.
Protecting Your Real Value
If you are a high-income business owner or executive in BC, Alberta, or Saskatchewan, stop assuming your generic company benefits plan covers your actual financial needs.
Take command of your financial security. Audit your current disability booklet, examine your total corporate compensation, and find out how much of your lifestyle is unprotected. Contact ADI Benefits Inc. today for a personalized analysis of your income exposure.